Car Loan Payment: Calculate It With Tax, Fees and Trade-In
To calculate a car loan payment, first work out the amount financed: the price minus your down payment, trade-in and rebates, plus any sales tax and fees you roll into the loan. Then apply the loan formula M = P × r ÷ (1 − (1 + r)−n), where r is the APR divided by 12 and n is the number of months. With the example numbers below, a $32,000 car becomes a $24,360 loan and a $482.36 monthly payment over 60 months. The rates here are examples only; your lender's offer decides the real figure.
🚗 Try Auto Loan Calculator now — freeOpen →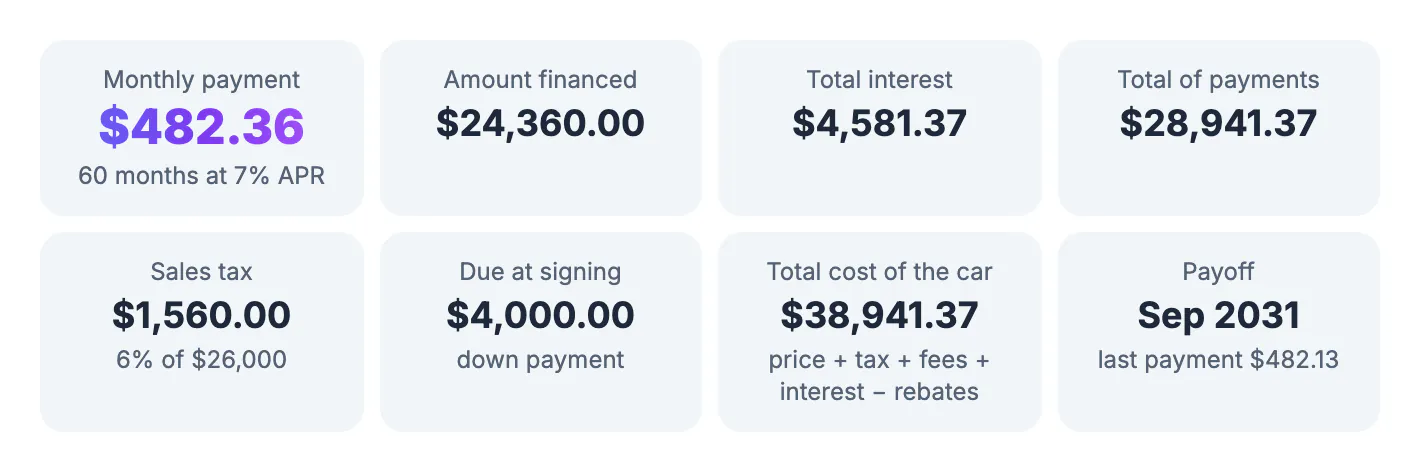
Dealers often negotiate around the monthly payment, because stretching the term makes almost any car look affordable. The payment depends on the amount financed, the rate and the term together, and small changes in each add up to thousands of dollars in interest. Doing the math yourself shows the total cost and whether a longer loan is worth it.
Step 1: find the amount financed
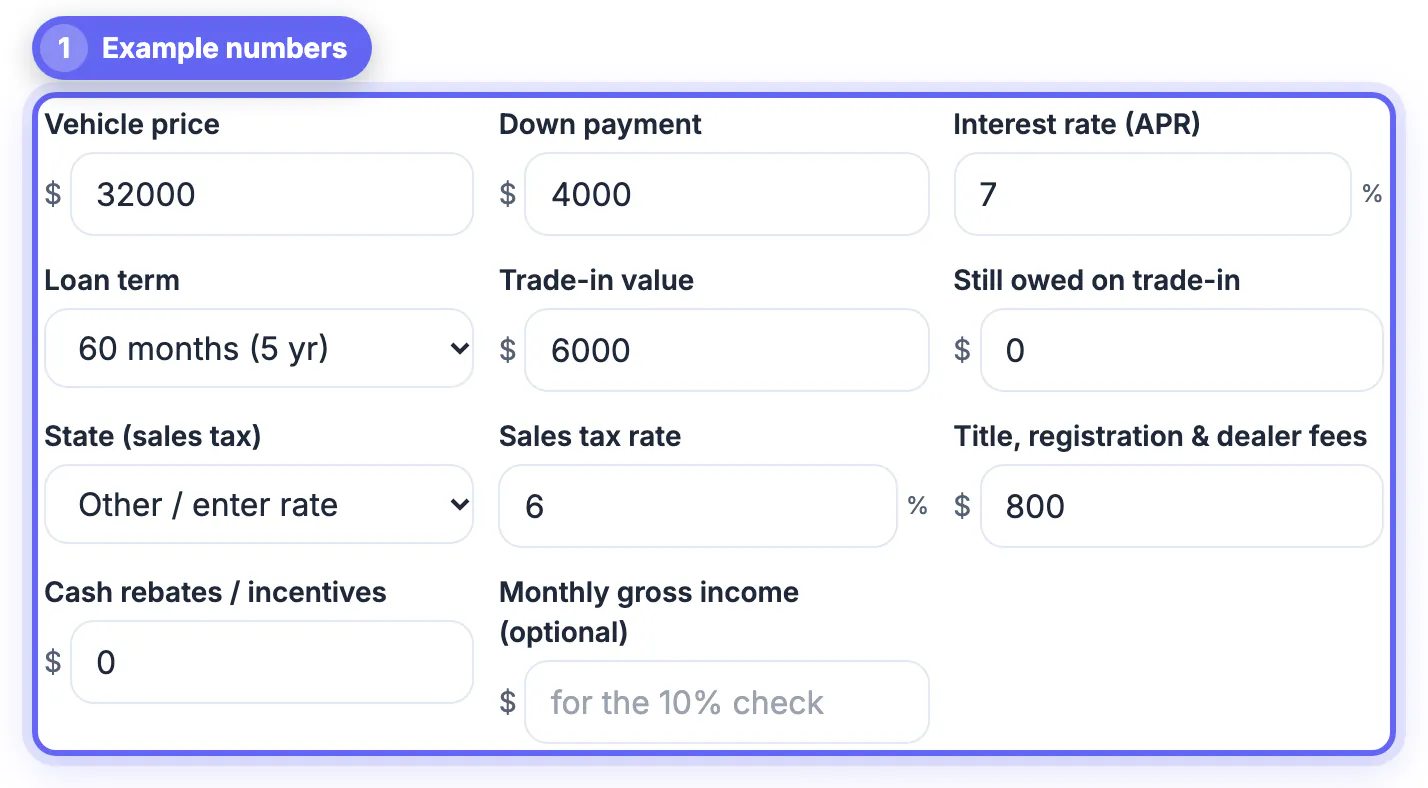
The example uses illustrative numbers, not a rate quote: a $32,000 car, $4,000 down, a $6,000 trade-in you own outright, a 6% sales tax rate, $800 in title, registration and dealer fees, and a 7% APR.
- Sales tax: in most states the trade-in is subtracted first, so tax = 6% × ($32,000 − $6,000) = $1,560.
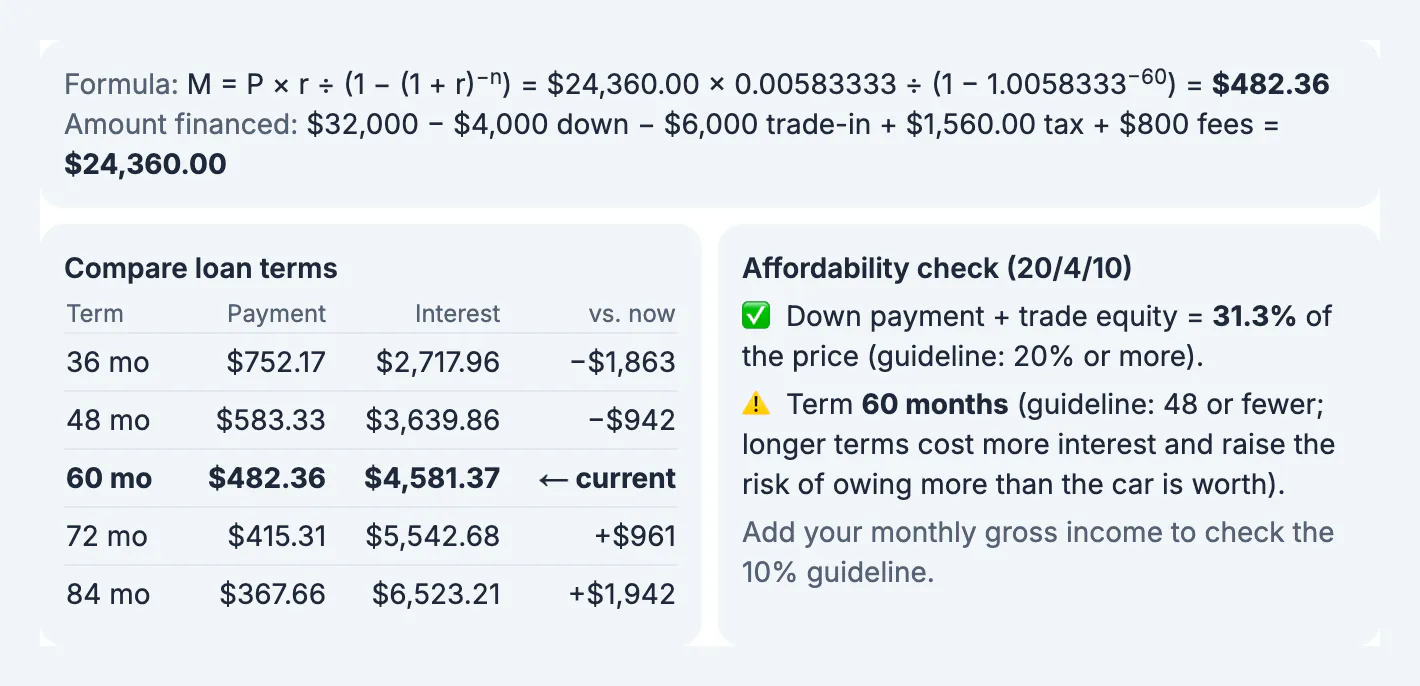
- Amount financed: $32,000 − $4,000 − $6,000 + $1,560 tax + $800 fees = $24,360.
- Negative equity: if you still owed $8,000 on a $6,000 trade-in, the $2,000 difference would be added to the loan.
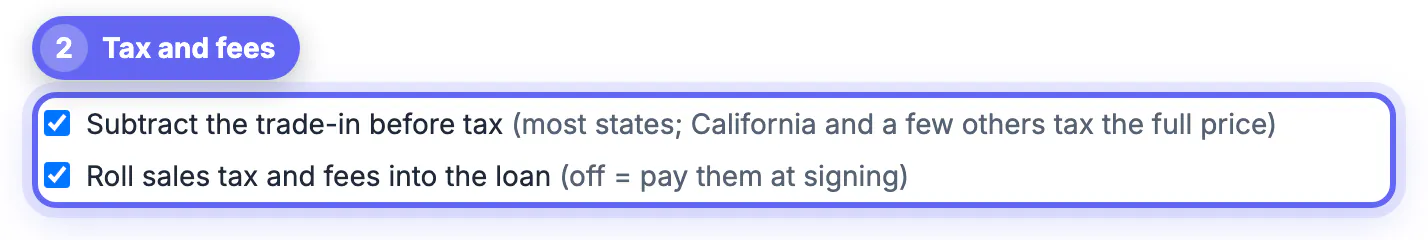
The auto loan calculator has a State menu that fills in the statewide base sales tax rate, which you can edit because counties and cities often add more. A checkbox lets you tax the full price instead, as California and a few other states do; here that would make the tax $1,920.
Step 2: apply the car loan payment formula
The monthly rate is 7% ÷ 12 = 0.5833%, or 0.0058333, and n is 60. Plugging in: M = 24,360 × 0.0058333 ÷ (1 − 1.0058333−60) = $482.36.
Over 60 payments you pay $28,941.37, of which $4,581.37 is interest. Adding the price, tax and fees gives a total cost of $38,941.37 for the car. At 0% APR the formula becomes simply P ÷ n. The calculator prints the formula with your numbers filled in, so you can check the result against a dealer's worksheet.
Interest is charged on the remaining balance each month, so early payments are mostly interest and later ones mostly principal. In the first month of the example, $142.10 of the $482.36 goes to interest and $340.26 reduces the balance. Paying extra toward principal early cuts total interest the most, as long as the lender has no prepayment penalty. Ask the lender to apply extra payments to principal, and confirm it on your next statement. Refinancing later can also help if rates fall or your credit improves.
Compare loan terms before you sign
The Compare loan terms table recalculates the same loan for 36 to 84 months. With the example amount and rate:
- 36 months: $752.17 a month, about $2,718 in interest
- 48 months: $583.33 a month, about $3,640 in interest
- 60 months: $482.36 a month, $4,581 in interest
- 72 months: $415.31 a month, about $5,543 in interest
Going from 48 to 72 months cuts the payment by $168 but adds roughly $1,900 in interest, and a long term raises the risk of owing more than the car is worth. The amortization schedule, by year or by month, shows how much of each payment goes to interest, and you can download it as a CSV.
Taxes, fees and the 20/4/10 check
- Roll in or pay upfront: untick Roll sales tax and fees into the loan to pay them at signing; the Due at signing card updates.
- Rebates: enter cash rebates or incentives. The calculator does not subtract them from the taxed price, because many states tax the price before a manufacturer rebate.
- 20/4/10 guideline: at least 20% down, a term of 48 months or less, and total car costs under 10% of gross monthly income. The example's $4,000 down plus $6,000 trade-in is 31.3% of the price, but the 60-month term is past the guideline.
Add your monthly gross income and the tool also shows the payment as a share of income. This is an estimate for comparison, not financial advice; your lender's disclosure is the final word.
Ways to lower the payment without a longer loan
- Bigger down payment: every $1,000 less financed at the example 7% rate over 60 months lowers the payment by about $19.80.
- Better rate: shop two or three lenders; the payment falls with each rate step, and interest falls faster.
- Cheaper car or fewer add-ons: extended warranties and packages financed into the loan also collect interest.
- Pay tax and fees upfront: if you have the cash, keeping them out of the loan avoids paying interest on them.
Run each change in the calculator and watch total interest as well as the monthly figure.
Step-by-step
Common mistakes to avoid
Pro tips
Frequently asked questions
How do I calculate a car loan payment?
Find the amount financed, then use M = P × r ÷ (1 − (1 + r)^−n), with r as the APR divided by 12 and n as the months. $24,360 at a 7% example rate for 60 months is $482.36.
Is sales tax included in a car loan?
It can be. Many buyers roll sales tax and fees into the loan, which raises the amount financed; you can also pay them at signing.
Does a trade-in reduce sales tax?
In most states the trade-in value is subtracted before tax. California and a few others tax the full price, so check your state's rule.
Is a 72-month car loan a bad idea?
It lowers the payment but costs more interest and increases the chance of owing more than the car is worth. In the example it adds about $960 of interest over 60 months.
What is the 20/4/10 rule for car buying?
A common guideline: put 20% down, finance for four years or less, and keep total car costs under 10% of gross monthly income. It is a rule of thumb, not a law.
A car payment starts with the amount financed: price minus down payment, trade-in and rebates, plus tax and fees if you roll them in. Run the formula, compare terms by total interest, and let the lender's disclosure, not the monthly figure, drive the decision.
Related guides
Browse more: all calculator guides · Auto Loan Calculator